
Kenya’s card payment tax landscape changed on 1 July 2026, when the Finance Act, 2026 brought interchange fees, merchant service fees and a wide range of payment services into the withholding tax and VAT net for the first time by express statute. If you are a bank, payment service provider, fintech, card scheme or merchant operating in Kenya, these changes are no longer proposals. They are in force, and banks have already begun passing the new 16% VAT charge through to customers as of 1 November 2026.
This article breaks down exactly what changed, why it happened now, and what banks, PSPs, fintechs and merchants should do about it.
Key Takeaways
- Interchange and merchant service fees are now expressly “management or professional fees” for withholding tax purposes.
- The definition of “royalty” has widened to cover payments for using card networks, payment platforms and processing systems, whatever the fee is called.
- Payment processing, settlement, merchant acquiring, gateway and aggregation services are now standard-rated at 16% VAT, reversing exemptions won in court in 2025.
- Both changes took effect 1 July 2026. Exposure may already be accruing for anyone who has not adjusted.
What Changed: Withholding Tax on Interchange and Merchant Service Fees
The Finance Act, 2026 amended section 2 of the Income Tax Act (Cap. 470) to bring interchange fees and merchant service fees arising from card payment transactions within the definition of “management or professional fee.” It also widened the definition of “royalty” to capture payments for the use of, or access to, proprietary digital payment card networks or platforms and payment processing systems.
This matters because the royalty definition applies whether the payment is periodic or transaction-based, and regardless of how it is labelled. A “network fee,” “assessment fee” or “processing fee” can fall within it based on what it actually pays for, not what the invoice calls it. The applicable withholding tax rate, and any relief under a double tax treaty, will depend on the nature of the payment and the recipient’s residence, which matters given that many card networks and platform licensors are based outside Kenya.
VAT on Payment Processing, Settlement, Merchant Acquiring, Gateway and Aggregation Services
The Act also narrows the VAT exemption for financial services. Five categories of payment service are now standard-rated at 16% when supplied for a fee:
- Payment processing: authorising and routing transaction data between the merchant, acquirer, card network and issuing bank
- Settlement: clearing transaction records and transferring funds from the issuing bank to the acquirer and merchant, net of fees
- Merchant acquiring: signing up merchants to accept card payments and linking them to issuers and card networks
- Gateway services: securely capturing and transmitting card details for authorisation
- Aggregation: enabling multiple merchants to accept payments through a single merchant account
Ordinary banking and traditional financial services remain exempt. The practical exercise for every participant in the payments chain is identifying which specific fees now fall on the taxable side of that line.
Why Now? KRA’s Assessments, Two Court Losses, and a Legislative Fix
This is not a sudden change in direction for Kenya Revenue Authority. KRA had already been raising assessments treating interchange fees as management fees and scheme fees as royalties. What changed is that this position was tested in court, and KRA lost twice in 2025.
In August 2025, the High Court ruled in favour of Pesapal, quashing a VAT assessment of roughly KES 76.8 million and holding that licensed payment service providers are “functionally equivalent” to banks for VAT exemption purposes. In October 2025, the Tax Appeals Tribunal ruled in favour of Kenswitch, setting aside a VAT assessment of roughly KES 41.6 million on switching and interchange-related fees. Both rulings held these services were exempt financial services.
Parliament’s response was to write KRA’s position into the statute. From 1 July 2026, the exemption these companies had just won in court no longer applies to the services listed above. The compliance question is no longer whether a fee qualifies as an exempt financial service. It is whether withholding tax and VAT have been correctly applied.
What This Means for Banks, PSPs, Fintechs and Merchants
Banks
Interchange income is now squarely withholding-taxable, and the network, assessment or processing fees banks pay out as scheme participants may be royalties. Banks should review correspondent, card scheme and processing agreements to confirm which party withholds on which fee, and check treaty relief where the counterparty is non-resident.
Payment Service Providers and Card Schemes
Supplying payment processing, settlement, merchant acquiring, gateway or aggregation services for a fee now means charging 16% VAT, and the exempt position won in Pesapal and Kenswitch no longer protects fees earned from 1 July 2026. PSPs should confirm VAT registration and re-price or re-paper contracts that assumed exemption.
Fintechs
Fintechs operating as aggregators, gateways or switches are inside the VAT net on fees they charge, and may simultaneously be withholding agents on fees they pay to platform or network licensors under the expanded royalty definition. Each fee needs to be mapped and classified separately.
Merchants
Merchants may now be obliged to withhold tax on merchant service and gateway fees they pay, while VAT at 16% on previously exempt services raises the cost of accepting card payments. Merchants should confirm who bears withholding responsibility under their contracts and budget for higher acceptance costs.
Immediate Action Steps
- Map every fee in your card payment flows and identify the payer, recipient and service involved.
- Classify each fee by substance, not label. “Network,” “assessment” and “processing” fees can all be royalties.
- Audit and update scheme, processing, merchant and software agreements to reflect the new tax position.
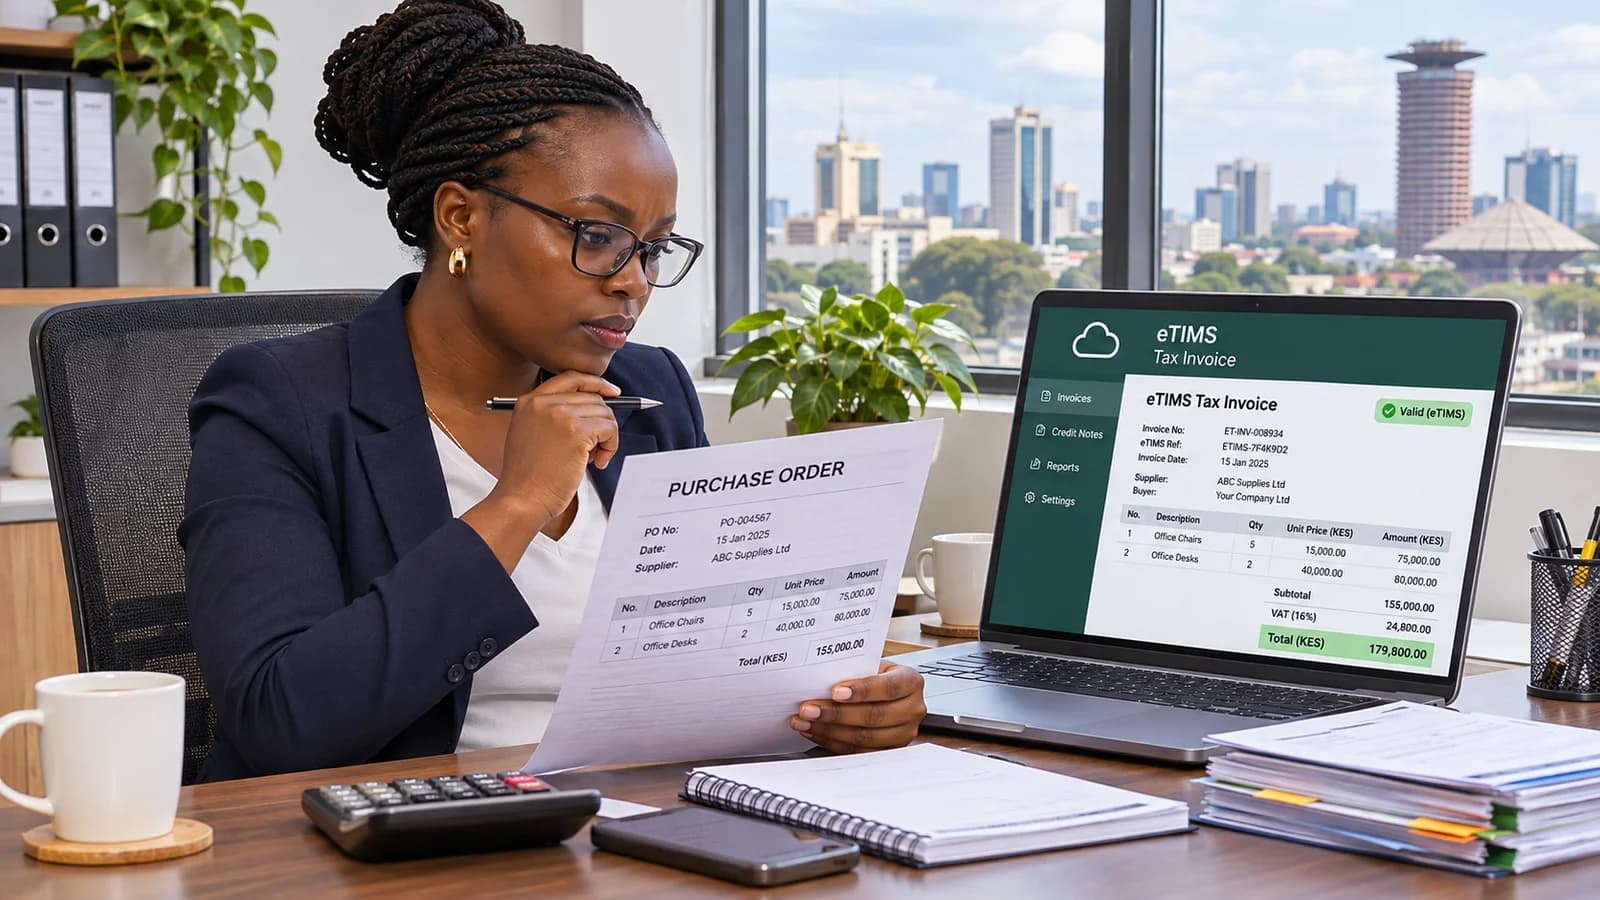
- Confirm VAT registration status and update invoicing to charge 16% VAT where required.
- Quantify exposure for the period since 1 July 2026. Under-withholding can carry penalty and interest risk under section 39A of the Tax Procedures Act.
- Put withholding tax and VAT compliance processes in place before KRA raises a query.
Frequently Asked Questions
When did Kenya’s new card payment tax rules take effect?
The withholding tax and VAT changes took effect on 1 July 2026 under the Finance Act, 2026. Banks began passing the new VAT charge through to customers from 1 November 2026.
Does the new VAT apply to M-Pesa and mobile money transfers?
The changes target payment processing, settlement, merchant acquiring, gateway and aggregation services connected to card payments. Ordinary mobile money transfers are generally treated separately, though businesses should confirm the specific tax treatment of their own fee structures.
Were these taxes already being charged before the Finance Act 2026?
KRA had already been assessing these fees under its existing interpretation, but that approach was successfully challenged in court twice in 2025, by Pesapal at the High Court and Kenswitch at the Tax Appeals Tribunal. The Finance Act, 2026 settled the question by statute.
Who is responsible for withholding the tax, the bank or the merchant?
This depends on the specific fee, the contractual arrangement between the parties, and who is making the payment. Businesses should review their payment and processing agreements to confirm where the withholding obligation sits.
What should banks, fintechs and merchants do now?
Map every card payment fee, confirm the correct withholding tax and VAT treatment, update contracts and invoicing, and quantify any exposure that may have accrued since 1 July 2026.
How MN Legal Can Help
MN Legal advises banks, payment service providers, fintechs and merchants on mapping card payment flows, reviewing and updating scheme, processing and merchant agreements, setting up withholding tax and VAT compliance processes, and responding to KRA audit queries or assessments. Get in touch with our tax and fintech team to assess your exposure under Kenya’s new card payment tax rules.
This article is for general informational purposes only and does not constitute legal or tax advice. For advice on your specific circumstances, please contact MN Legal Advocates LLP.